Pricing to Sell Above 7% Rates
Pricing to Sell Above 7% Rates
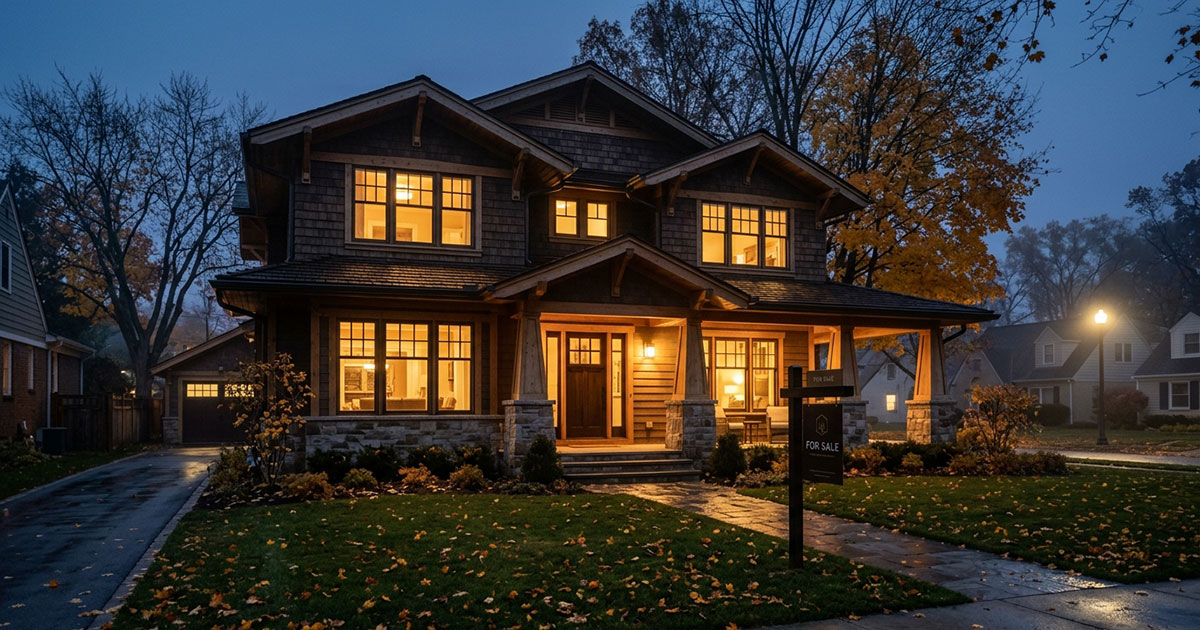
Selling a home in November requires a disciplined pricing strategy as mortgage rates linger above seven percent and buyer activity slows. By pricing aggressively from launch, understanding the crucial initial two-week window, and offering targeted mortgage rate buydowns instead of arbitrary price cuts, homeowners can attract serious buyers, protect their equity, and close deals before winter arrives.
The November Reality
Entering the housing market in November presents a distinct set of challenges and opportunities that look radically different from the frenzied open houses of spring. With borrowing costs hovering stubbornly above seven percent, the pool of casual prospective buyers has evaporated, leaving behind a smaller contingent of highly motivated, highly discerning house hunters. These buyers are scrutinizing every monthly payment calculation against steep interest costs, rising property insurance premiums, and municipal property taxes. At the same time, nationwide real estate trends show that active inventory has accumulated heading into the fourth quarter as properties linger on multiple listing services far longer than sellers originally anticipated. When homes sit unsold, prospective purchasers inevitably begin to wonder what underlying flaws might be hiding behind the fresh coat of paint. For sellers who entered the market with unrealistic expectations formed during previous record-setting seasons, the current environment demands an immediate pivot toward grounded valuation and sharp financial positioning.
The Critical Initial Window
The most critical asset any seller possesses when listing their property is the organic momentum generated during the initial fourteen days on the market. Modern real estate search engines and automated alert systems push newly listed homes directly into the email inboxes and smartphones of active buyers the moment a property is published. This brief two-week period represents the absolute peak of buyer interest and showing volume. If a home is priced even three to five percent above fair market value during this opening phase, serious buyers simply swipe past it or refuse to schedule in-person tours, recognizing that high mortgage rates leave zero room for speculative overpaying. Once that introductory honeymoon window closes without receiving viable offers, the listing becomes stale, accumulating days on market that actively undermine the seller’s negotiating leverage. Savvy sellers resist the temptation to pad their list price with extra negotiating room, opting instead to price precisely at or slightly below prevailing market comps to ignite immediate traffic and spark urgent decision-making.
Strategic Price Corrections
When an active listing fails to generate meaningful showing activity or written purchase offers within the first two to three weeks, an immediate and decisive pricing adjustment becomes essential. A common tactical mistake made by frustrated homeowners is executing gradual, incremental reductions of one or two thousand dollars over several consecutive weeks. These micro-adjustments project vulnerability, signaling to experienced buyers and aggressive investors that the seller is growing increasingly anxious and will eventually yield to lowball offers. Furthermore, minimal price decreases fail to trigger the automated alert mechanisms of real estate portals or move the listing into new buyer affordability brackets. An effective pricing correction should be swift, singular, and significant, typically representing a reduction of three to five percent. A substantial correction changes the narrative surrounding the property, effectively relaunching the listing to an entirely fresh cohort of pre-approved buyers who were priced out of the initial asking price and are eager to secure a home before the upcoming holidays.
Rate Buydowns Over Price Drops
In a high-interest lending landscape where mortgage rates exceed seven percent, the primary pain point for buyers is not necessarily the purchase price itself, but rather the monthly principal and interest payment. Forward-thinking sellers can achieve far greater impact by offering targeted seller concessions toward temporary or permanent mortgage rate buydowns rather than slashing their asking price by tens of thousands of dollars. For instance, a seller offering twenty thousand dollars in closing concessions to fund a temporary two-one buydown can effectively lower the buyer’s mortgage rate by two full percentage points in the first year and one percentage point in the second year. This arrangement slashes the buyer’s monthly out-of-pocket obligation by hundreds of dollars right when moving and furnishing expenses are highest. From the seller’s financial standpoint, allocating a concession toward financing costs preserves the headline sales price, protects neighborhood comparable values, and solves the buyer’s immediate affordability crisis at a fraction of the cost of a massive price reduction.
Eliminating Deal Friction
Beyond upfront pricing and financing concessions, maintaining pricing integrity in late autumn requires eliminating friction points that could derail an appraisal or an underwriting review. With lenders exercising heightened scrutiny over borrower debt-to-income ratios, unexpected repairs uncovered during home inspections frequently cause buyers to panic and terminate contracts. Sellers who take the proactive step of conducting pre-listing home inspections and addressing deferred maintenance before welcoming the first buyer can decisively neutralize these deal-killing surprises. Providing clear documentation regarding the operational health of heating systems, the structural condition of roofs, and current homeowners insurance insurability provides cautious purchasers with the psychological reassurance they crave. When a property is positioned as genuinely turnkey and free of immediate capital expenditure demands, qualified buyers are far more willing to commit their hard-earned capital at current borrowing rates without demanding punitive price concessions or escrow holdbacks at the closing table.
Winning the Late-Autumn Market
Navigating the late-autumn real estate environment when mortgage rates hover above seven percent demands pragmatism, swift adaptability, and an acute understanding of buyer psychology. While spring sellers could rely on frantic bidding wars and emotional offers to cover for ambitious valuations, November sellers must execute their transactions with surgical precision. By aligning initial asking prices strictly with realistic comparative sales, treating the first fourteen days on market as an irreplaceable launch pad, and utilizing seller-funded rate buydowns to directly ease monthly financing burdens, homeowners can cut through seasonal stagnation. Serious buyers remain in the market, ready to act decisively on homes that demonstrate fair value and thoughtful financial flexibility. Sellers who embrace these proactive pricing mechanics will not merely avoid the costly trap of languishing on the market through the winter freeze, but will successfully close their transactions on favorable terms and secure their hard-earned home equity.
Alex Karimi
RE eBroker
21704 West Golden Triangle Rd Suite 307 Santa Clarita, CA 91350
Email: alex@alexkarimi.com
Phone: (310) 776-2706
I take the time to listen carefully to understand my client’s needs, wants and concerns. I will be ready to take quick action when required and spend more time with those who aren’t quite sure which direction to take. My genuine concern for my client’s best interests and happiness ensures the job is done!